- 15 Songs That Sparked Generations of Activists - October 23, 2026
- 20 Books That Brought American Myths to Life - October 23, 2026
- The True Origins of America’s Greatest Rock Bands - October 23, 2026
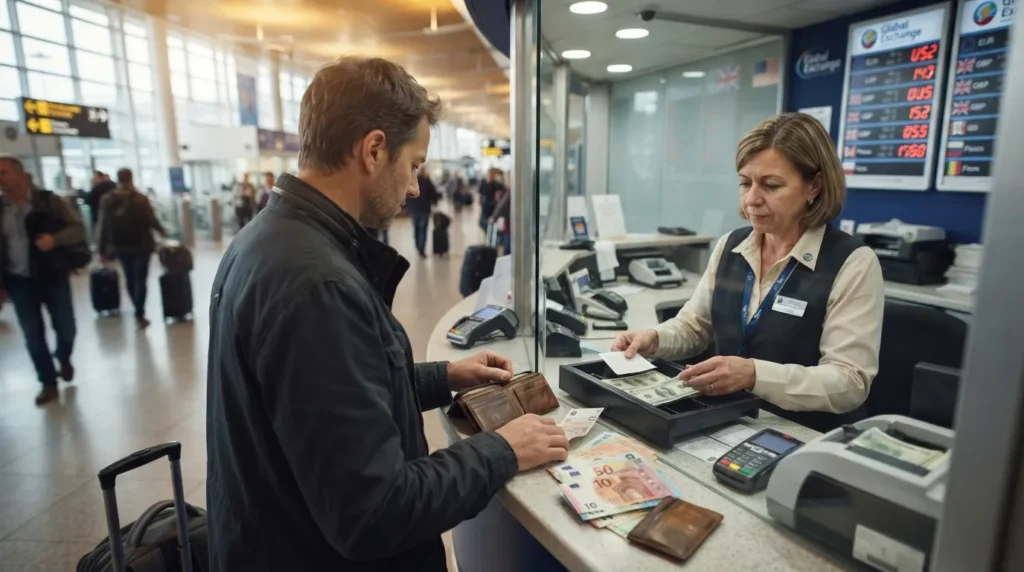
You land tired, the exchange sign is glowing, and foreign cash is two minutes away. That convenience is real, and so is the price. The cost usually hides inside the exchange rate, where no receipt line points to it.
The 16 traps below run from the quietly annoying to the genuinely expensive. Some have nothing to do with the exchange desk. A few are waiting at the card terminal and the ATM, and the last one is the habit that ties all the others together.
#16 – Overlooking the Mid-Market Benchmark
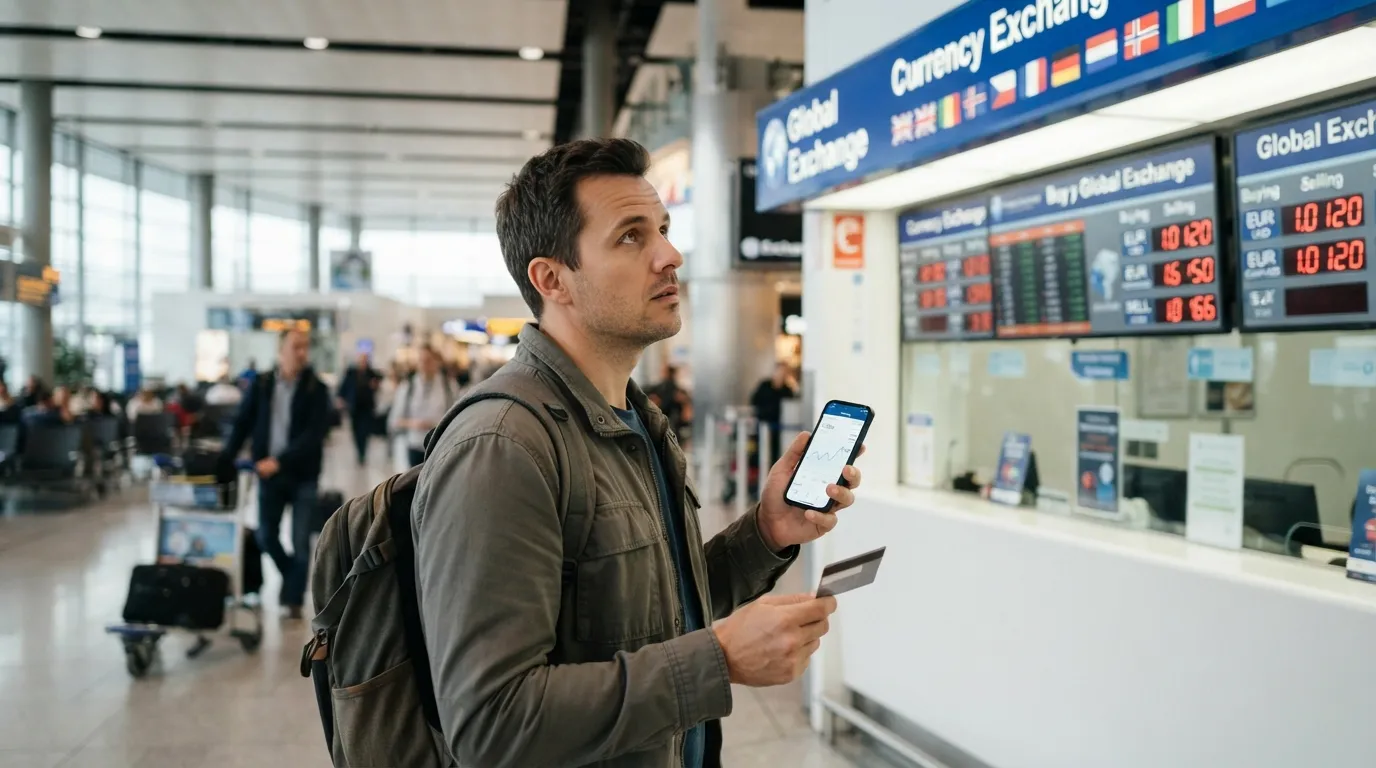
Most travelers never look up the real interbank rate before they exchange. Without that number, an airport offer is just a friendly-looking figure with nothing to compare it to.
Airport desks face little competition, so their pricing reflects a captive crowd rather than the open market. Cards from major networks often land much closer to the benchmark when used correctly abroad.
Check the baseline first, or you can’t tell a fair rate from a bad one.
The next trap hides behind a sign that sounds like good news…
#15 – Falling for “No Commission” Claims
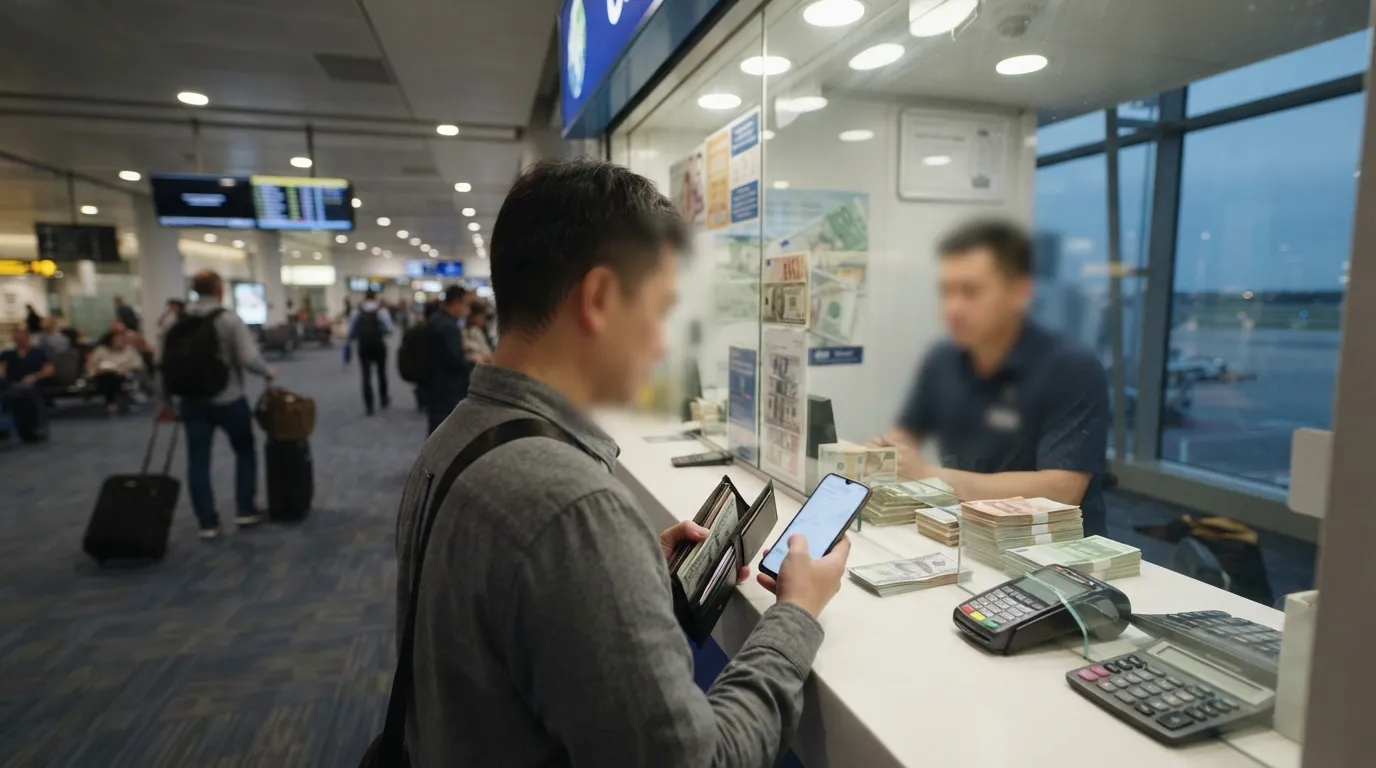
A big zero-commission sign pulls your eye away from the number that matters, the rate itself. The profit doesn’t vanish. It moves into the gap between the buy and sell prices instead of showing up as a separate fee.
That makes the true cost hard to work out while a line forms behind you. No explicit fee does not mean a competitive deal.
The spread can cost more than a plain, visible commission would have.
The next one happens at the card machine, and it takes a single button press…
#14 – Accepting Dynamic Currency Conversion at Terminals
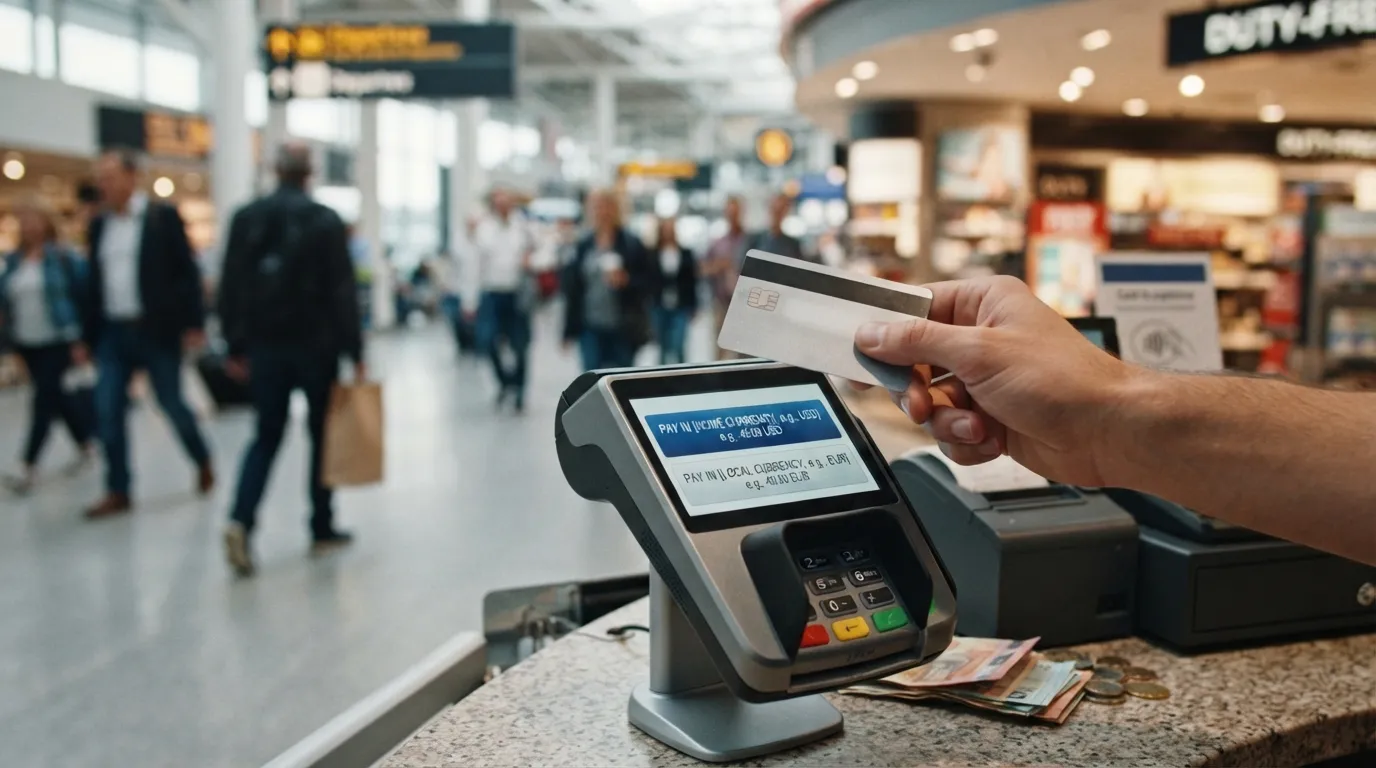
The screen asks if you’d like to pay in your home currency. It sounds helpful, even considerate. But choosing it routes the conversion through the merchant or ATM operator instead of your card network, so the rate is set outside the standard process.
Choose the local currency instead, and your card issuer applies its own terms.
Quick Compare
- Pay in local currency: the card network converts, then your issuer applies its own terms.
- Pay in your home currency: the merchant or ATM operator sets the rate.
- Your move: decline the prompt and select the local currency.
That one tap can decide whether a purchase stays reasonable or quietly gets more expensive.
Next, a fee that waits until the receipt prints…
#13 – Ignoring ATM Operator Fees
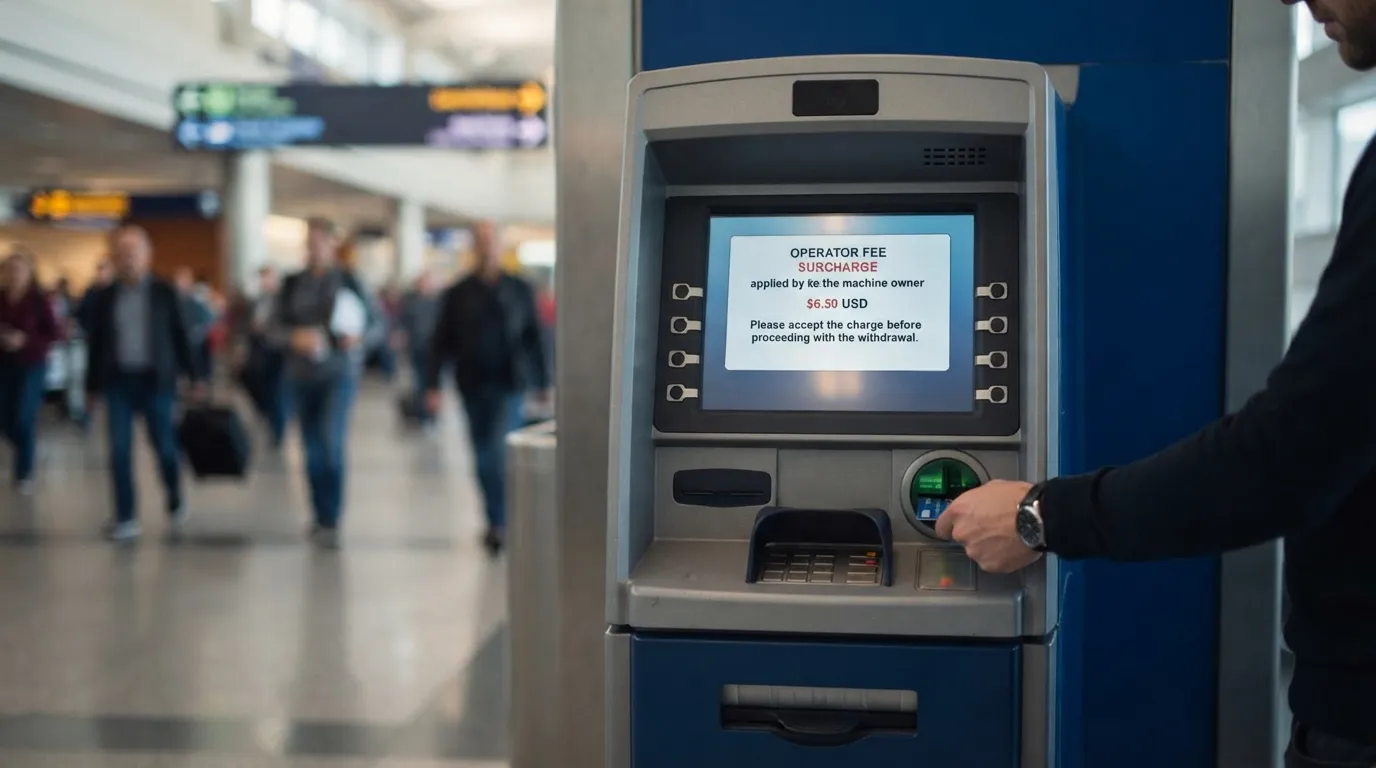
Independent machines in terminals often add their own surcharge on top of whatever your bank charges. The fee can differ from machine to machine, and it may appear only after your card is already in.
Bank-affiliated ATMs inside the destination country tend to carry lower operator fees, or none. Checking the machine’s network before you withdraw helps you dodge the steepest ones.
The operator fee stacks with every other cost, and it’s easy to miss until the receipt prints.
Next, a trap that punishes the smallest, most rushed exchanges…
#12 – Triggering Minimum Transaction Charges
Some exchange points charge a flat minimum fee no matter how little you change. A small emergency exchange can end up with a painfully high effective cost.
Larger, planned exchanges spread any fixed fee thinner. Arranging currency before you leave removes the need for last-minute minimums entirely.
Minimum fees hit hardest on the quick, small exchanges travelers make when they’re short on time.
Next, the leftover cash sitting in your pocket on the way home…
#11 – Underestimating Buy-Back Losses on Leftover Cash
Unused foreign notes often get a worse rate when you sell them back than the rate you paid to buy them. The round-trip spread takes a bite out of whatever is left.
Planning the amount you actually need reduces your exposure to that second, weaker rate. Some travelers keep a small emergency balance of a major currency at home instead.
The buy-back gap turns leftover cash into one more cost, not a neutral remainder.
Next, the pressure that makes all of these traps work…
#10 – Leaving Exchange Until the Last Minute
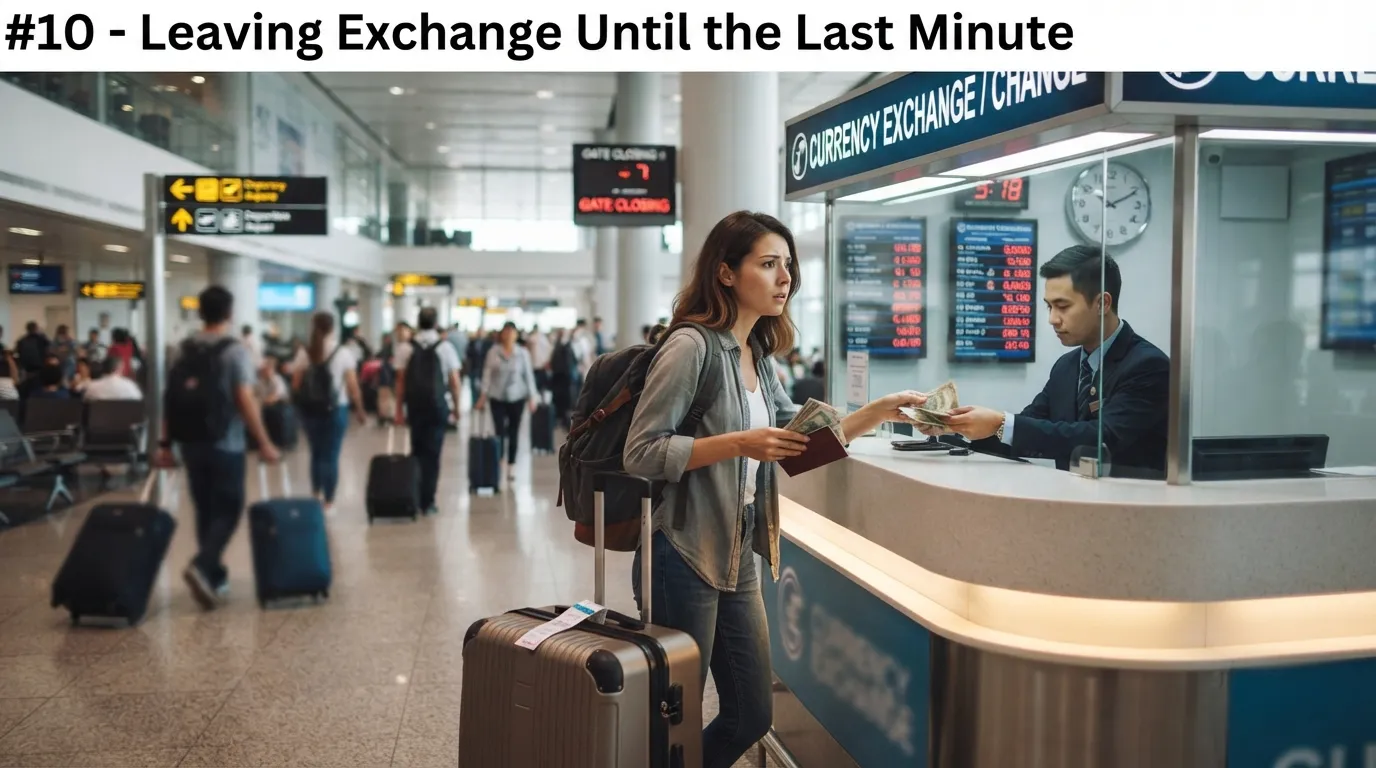
Rushing at the airport leaves no time to compare options or walk away from a bad offer. Urgency hands the pricing advantage to whoever is behind the counter.
Ordering currency or loading a card days ahead gives you time to compare and takes the pressure out of the decision.
When you can’t walk away, you rarely get the best deal.
Next, the desks that look like alternatives but play by the same rules…
#9 – Trusting Hotel Desks and Terminal-Adjacent Counters
Hotel desks and some counters near the terminal work under the same captive conditions as airport kiosks. Their rates reflect the same lack of competition.
Local bank branches or destination ATMs after arrival usually do better. Walking past every airport-adjacent option keeps that advantage in your pocket.
The convenience of a nearby desk carries a premium that can repeat across a whole trip.
Next, a trap that stacks one bad rate on top of another…
#8 – Allowing Multiple Currency Conversions
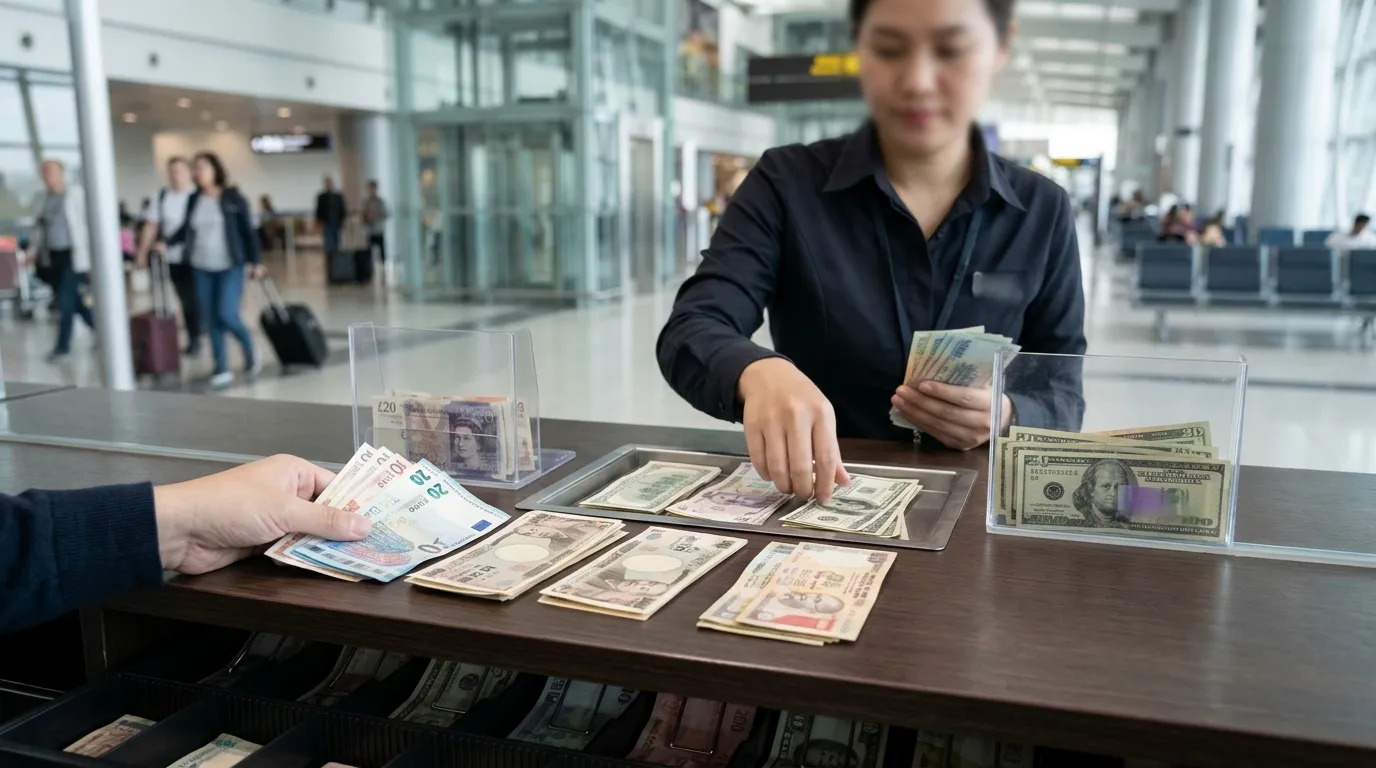
Changing one currency into a second, then a third, adds a spread at every step. Airport desks sometimes route less common currencies through an intermediate one, and you pay the margin each time.
Direct paths, or using a card in the destination currency, skip the extra layers. Ask about the full conversion chain before you agree to anything.
Worth Knowing
- Every conversion step carries its own margin.
- Less common currencies may be routed through an intermediate one.
- Asking for the full chain up front costs nothing.
- A card used in the destination currency skips the extra layers.
Every extra conversion adds its own margin, and you’re the one who pays it.
Next, a fee that lives in your wallet before you even leave home…
#7 – Carrying Cards with Foreign Transaction Fees
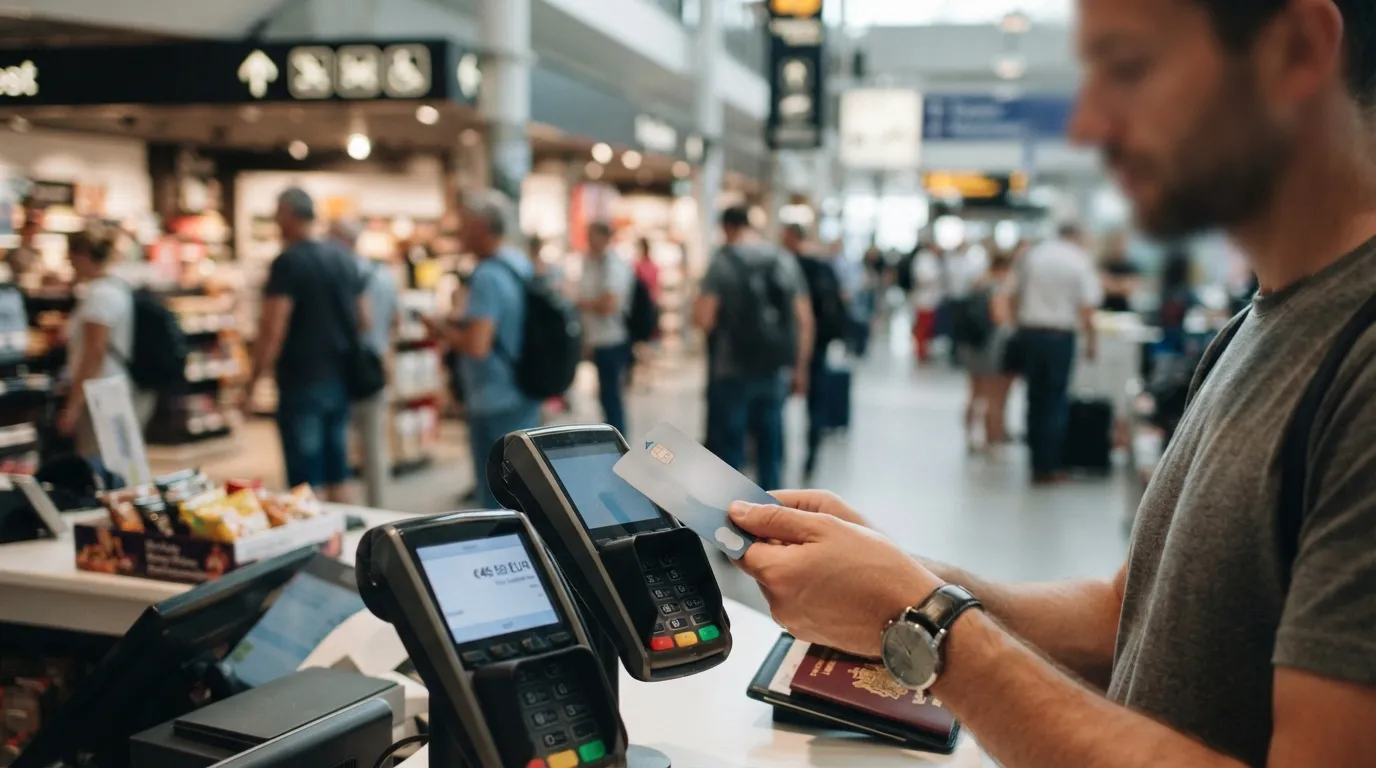
Many standard cards add a percentage to every foreign purchase or withdrawal. It sits on top of the network rate and shows up on your statement later, long after the moment has passed.
Several issuers offer no-foreign-transaction-fee cards that remove that layer completely. Switching before you travel takes the percentage out of the equation.
The fee looks small on each purchase, but it adds up across a whole itinerary with no warning at the register.
Next, why taking out cash in small bites can backfire…
#6 – Making Frequent Small ATM Withdrawals
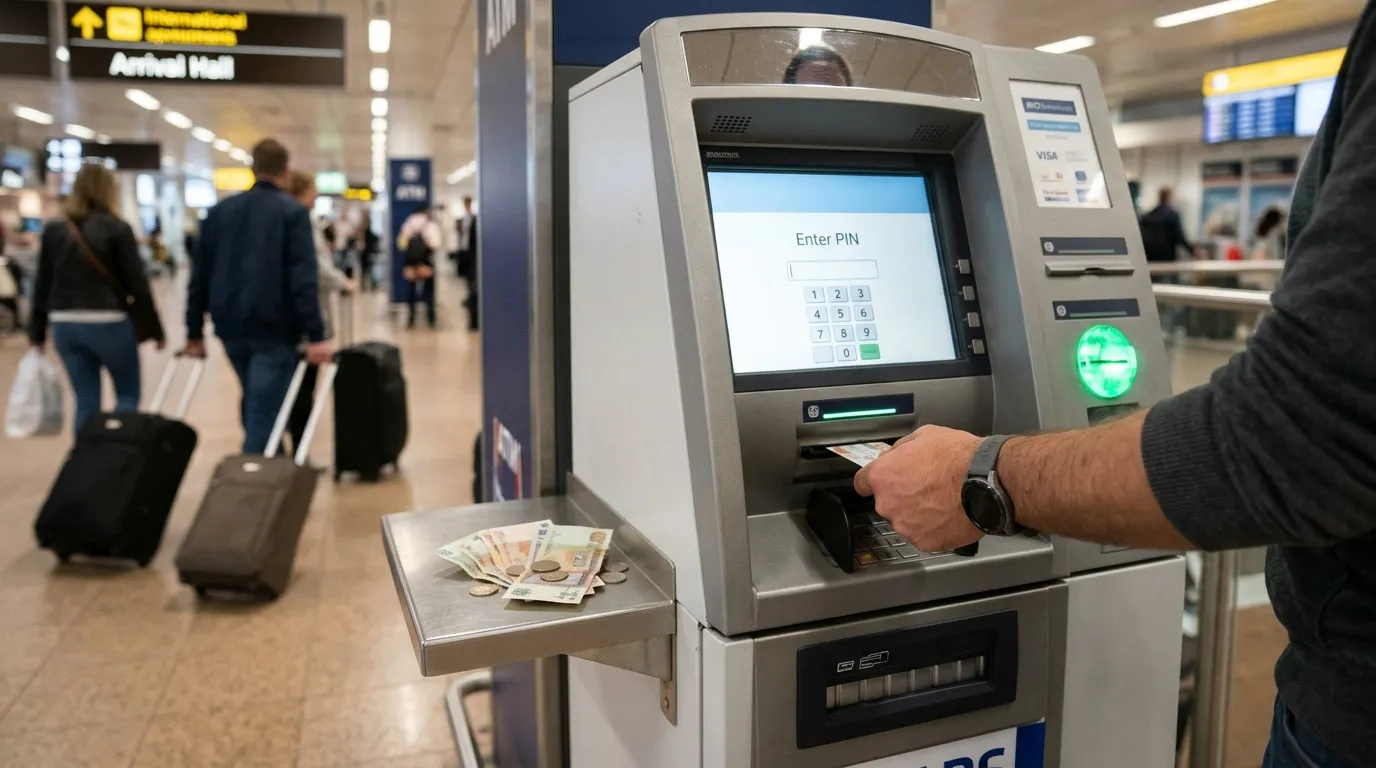
Each withdrawal can trigger an operator fee and a bank charge. Many small trips to the machine multiply those fixed costs.
Larger, less frequent withdrawals shrink the impact of flat fees. Destination bank ATMs often keep operator charges modest when used this way.
The fee structure rewards fewer, larger withdrawals over many small ones.
Next, the full price of a single withdrawal, which rarely shows up in one place…
#5 – Missing the Full ATM Fee Stack
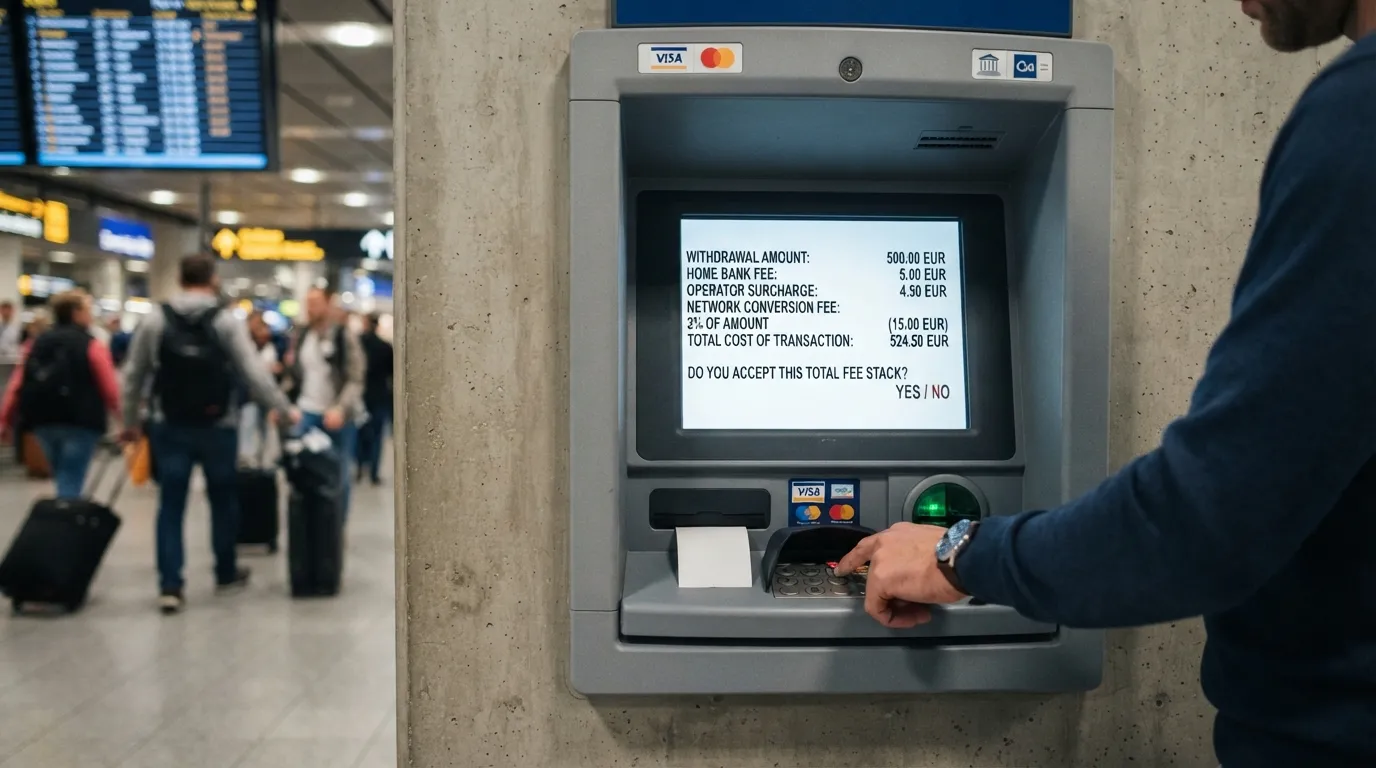
One withdrawal can combine your home bank’s fee, the foreign operator’s surcharge, and a network conversion element. Travelers often notice just one of them on the receipt.
Review the full fee disclosure before you confirm the amount. Some issuers reimburse operator fees, which changes the real cost.
The combined stack is rarely shown in one place until the transaction is already done.
Next, a card habit that turns convenience into one of the priciest moves on the list…
#4 – Treating Credit Cards as Cash Sources
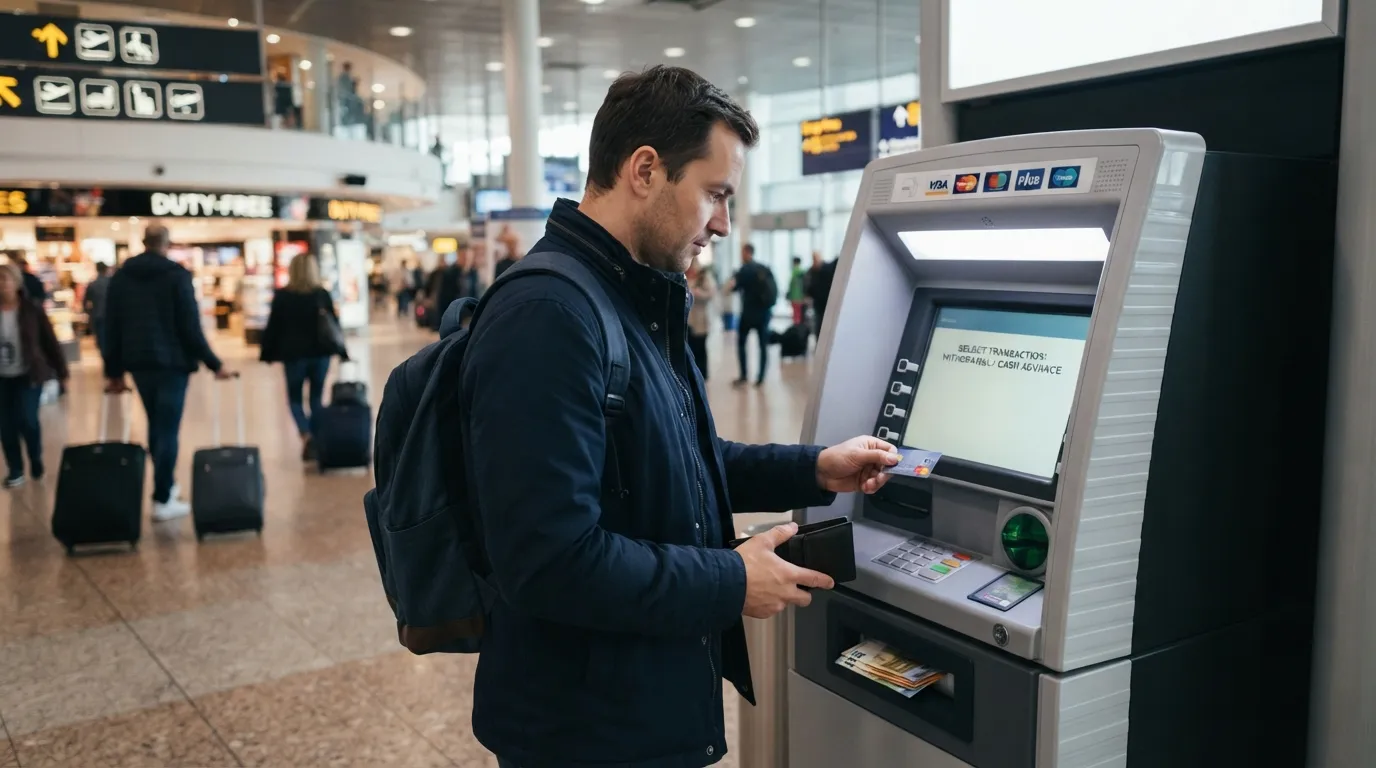
A credit card cash advance starts costing you right away, with interest and separate fees. Even a card with no foreign transaction fee treats an advance differently from a purchase.
Debit or prepaid travel cards avoid that classification. Using them for actual cash needs keeps the cost structure simpler.
At a Glance
- Interest and separate fees can begin immediately.
- An advance is treated differently from a regular purchase.
- A no-foreign-fee card doesn’t change that.
- Debit or prepaid travel cards sidestep the advance classification.
What looks like a handy option can be one of the most expensive ways to get local currency.
Next, the machines you walk past without a second thought…
#3 – Defaulting to Airport or Tourist-Zone ATMs
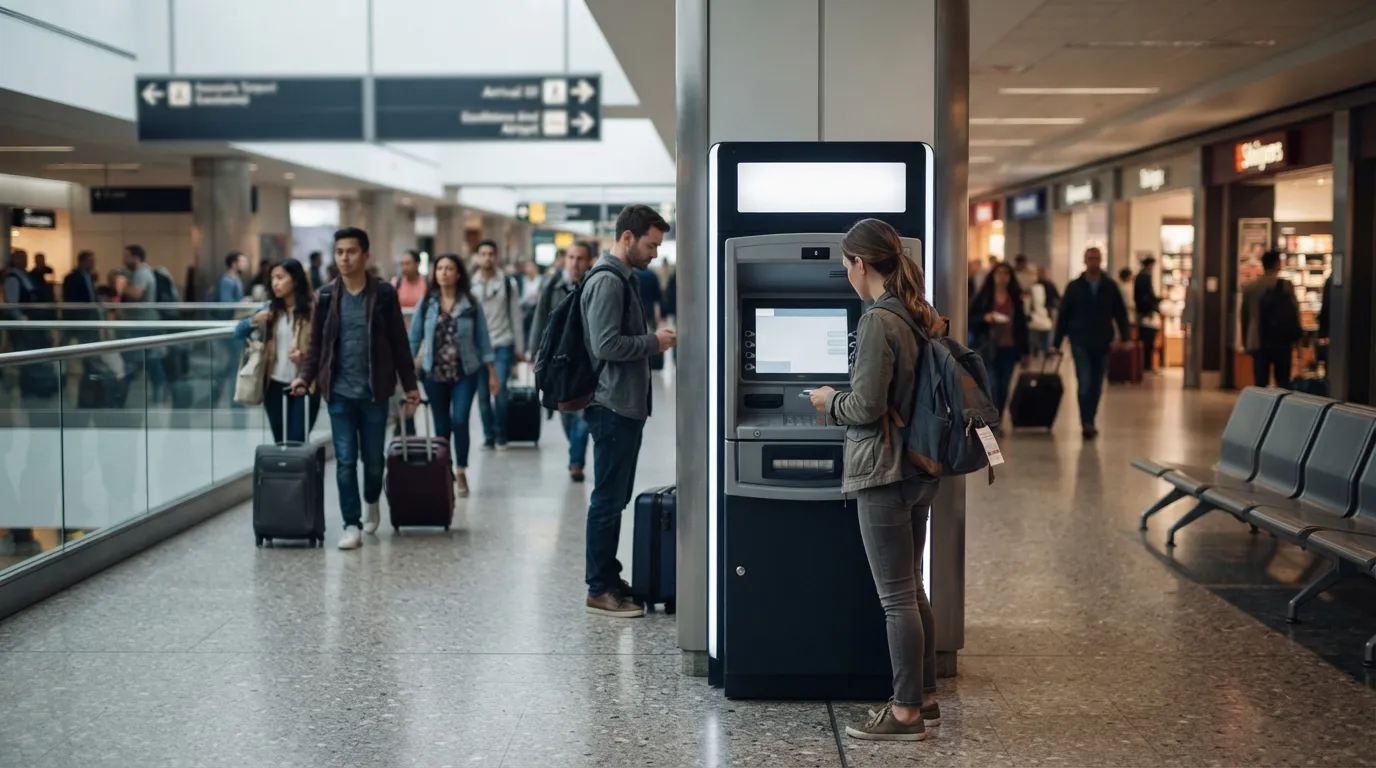
Standalone machines in high-traffic areas often carry some of the highest operator fees. Bank branches in the destination city usually offer better terms and clearer fee information.
For larger cash needs, a short walk or ride to a local bank machine can pay off. Airport machines are built for the captive crowd first.
Where you stand when you withdraw can decide which fee schedule you pay.
Next, the move that makes most of this list irrelevant…
#2 – Skipping Pre-Travel Currency Options
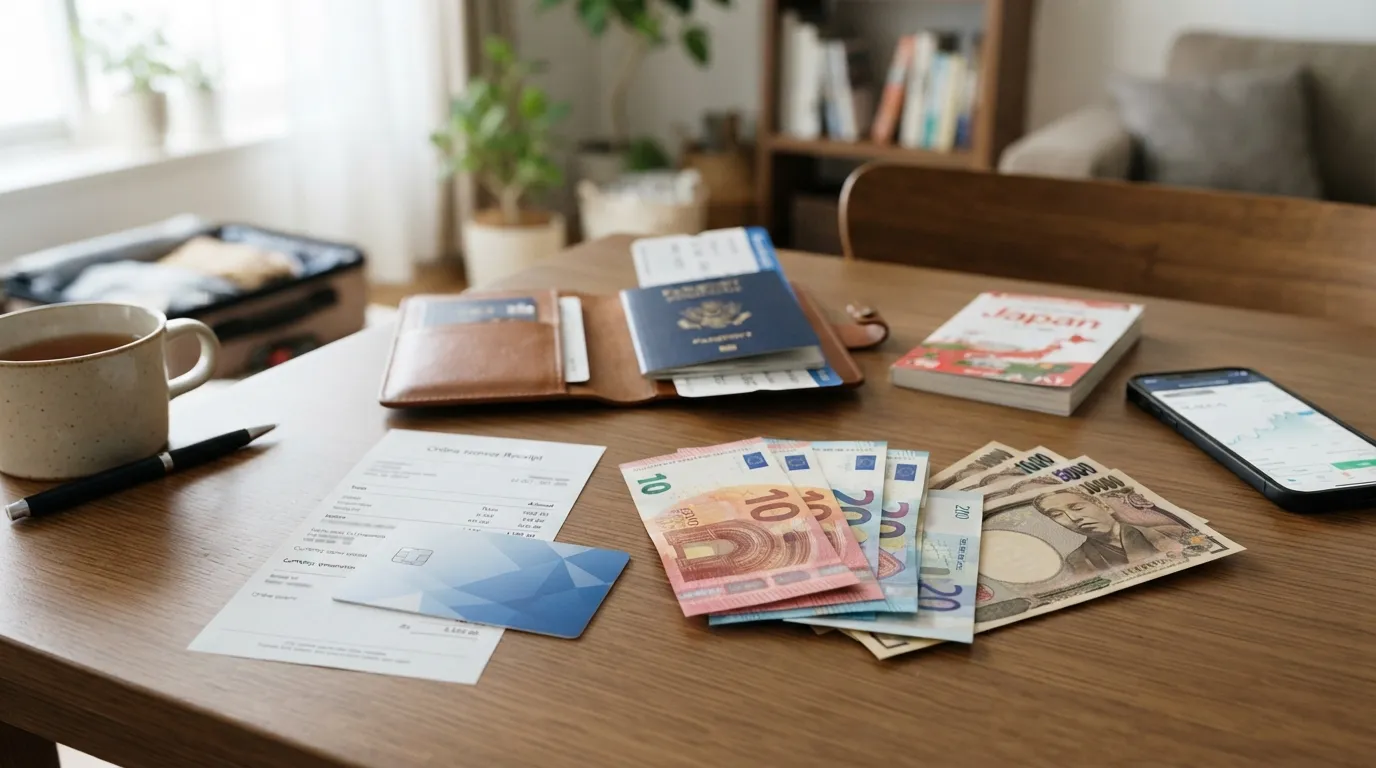
Ordering currency or loading a multi-currency card days before departure lets you settle on terms without airport pressure. Many providers let you compare rates and offer delivery or pickup.
In most cases, this removes the need for any terminal transaction at all. You can also check what you received against what the airport would have offered.
Why It Stands Out
- You get time to compare providers instead of reacting to one sign.
- Delivery or pickup options fit different schedules.
- It often removes the need for any terminal transaction.
- You can check the result against the airport’s offer.
Preparing ahead gives you something the airport never will: time to say no.
And the biggest trap of all is the one most travelers never question…
#1 – Treating the Airport Kiosk as the Default Solution
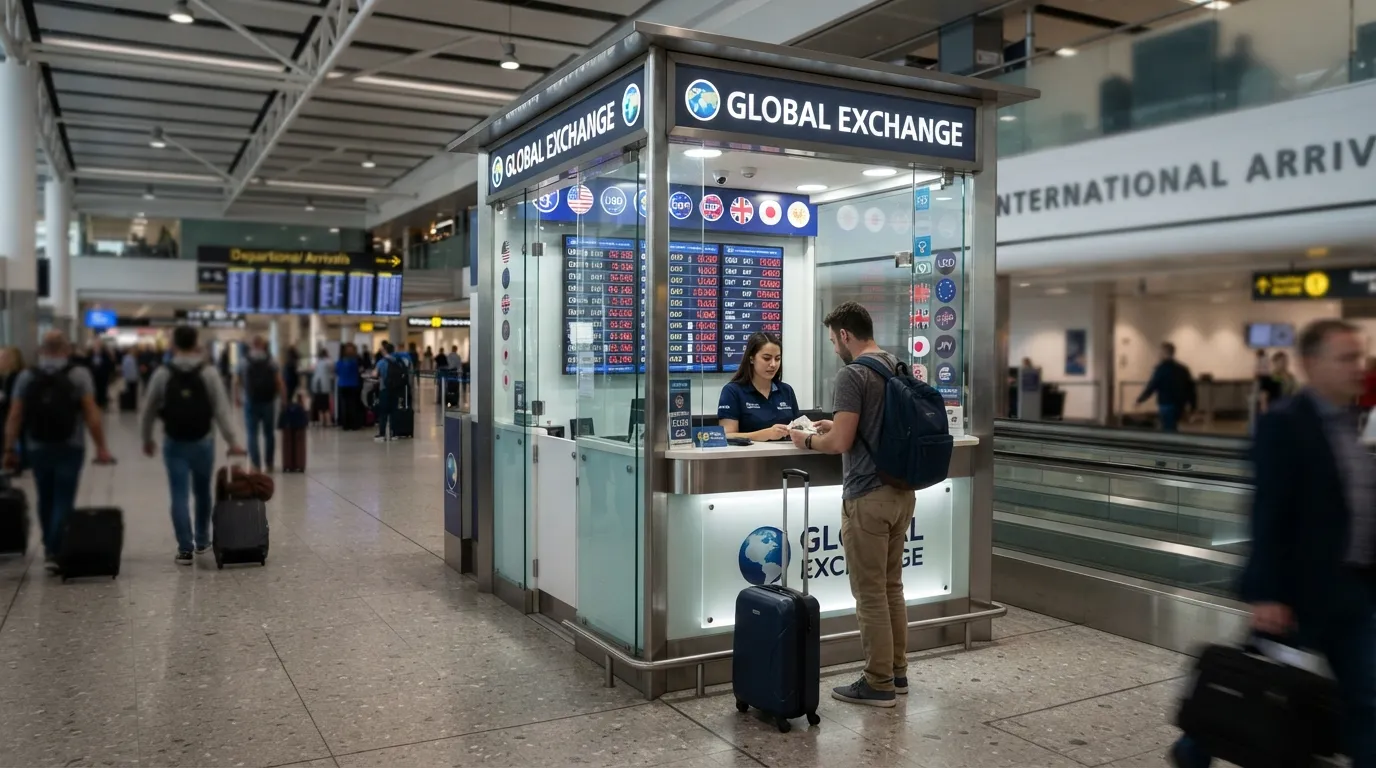
The terminal exchange desk packs poor rates, hidden spreads, and the highest convenience premium into one spot. Every other option on this list avoids at least one of those layers.
Walk past the desk and use a prepared card or a destination ATM, and the savings are the clearest of any fix here. The kiosk is a last resort, not a plan.
The default choice is often the most expensive one on offer at that moment.
The airport exchange desk isn’t a villain. It’s a business model built on your hurry, and most of these traps lose their bite once the hurry is gone.
Set up a card or pre-ordered currency before you leave, and always choose the local currency at the terminal. Which of these traps have you run into, and what workaround saved you? Tell us in the comments.
CEO-Co-Founder